When public companies release IFRS financial statements, most sellers scroll right past the dry accounting tables. That's a mistake: buried inside those multi-page filings is the real story of who pays for—and profits from—a marketplace ecosystem.
On October 28, 2026, Ozon reported its third-quarter results. The headline takeaway: the marketplace has officially stopped being a simple online retailer and turned into a high-margin services platform. While sellers fight to defend margins against inflation and rising ad bids, the platform itself is posting remarkable financial resilience.
The Services Gap: Platform Earnings From Sellers Outpace GMV Growth
Look at the key numbers for the quarter:
- GMV (Gross Merchandise Value) grew 42% year-over-year to 1.56 trillion rubles (crossing 4 trillion rubles for the first 9 months).
- Delivered orders jumped 76% to 1.18 billion. That tells a clear story: shoppers are ordering more often, while average order value keeps shrinking.
- Total group revenue climbed 63%, topping 421.2 billion rubles.
- Adjusted EBITDA surged 124% to 93.0 billion rubles, and net profit came in at 3.7 billion rubles—even after Ozon booked 30.1 billion rubles in estimated impairment reserves for damage across 11 warehouses hit by drone attacks.
- Fintech (Ozon Bank) generated 27.1 billion rubles in pre-tax profit as revenue rose 57%.
For a seller, though, the sharpest insight sits in comparing two diverging lines:
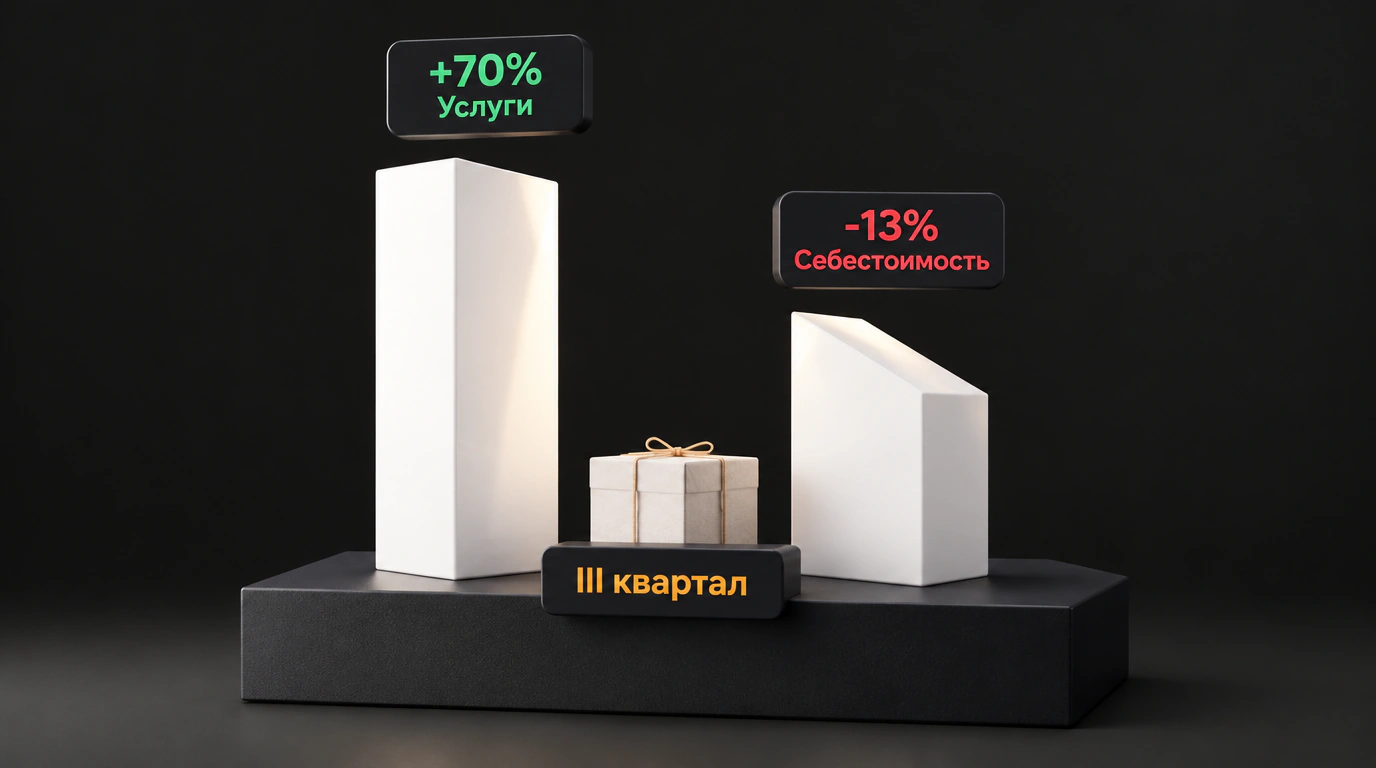
- Ozon's services revenue (commissions, logistics, advertising, subscriptions, and payment processing) jumped 70% to 275.7 billion rubles. Service fees are growing nearly twice as fast as merchandise turnover itself (+42%).
- The marketplace's own fulfillment cost per order simultaneously fell 13% to 150 rubles.
Through warehouse robotics and denser courier routing, Ozon learned how to move parcels cheaper. Yet sellers aren't paying less for logistics or shelf visibility—on the contrary, the platform is taking a larger slice of the pie. Industry surveys on marketplace seller net profit trends reflect that pressure, and our breakdown of real unit profitability on marketplaces confirms the ongoing squeeze on net margins.
What This Means for Your Wallet: Ads, Deductions, and Fintech Float
Why did services revenue skyrocket? Any active seller knows the answer: organic storefront traffic is effectively dead. To keep orders flowing, you have to pour cash into auction tools—"Stencils" (Trafarety), search promotion, and brand shelves. Advertising share of revenue (ACoS / DRR) has climbed over the past year from the usual 5–7% to 12–18%, hitting 25% in cutthroat categories like apparel and beauty.
In the filing, ad revenue and dimension-mismatch fines sit neatly inside overall services revenue, yet they are what drive the marketplace's record margins. On top of that, Ozon holds 364.2 billion rubles of seller and buyer funds in its settlement cycle, earning massive interest income on the float.
If Ozon's combined deductions on your SKU (category commission + FBO/FBS logistics + payment processing + search ads) exceed 38–40% of the retail price, that product is in the danger zone. Even a minor spike in return rates will push the listing into a direct cash loss.
How do you operate in this reality? First, run a weekly cleanup of your ad campaigns: kill non-converting keywords and enforce hard daily spend caps. Second, bake ad-auction costs into your baseline unit economics back when you're still sourcing from suppliers. The marketplace is getting richer on services—and the only sellers thriving alongside it are the ones who manage every cost line with surgical discipline.